
By Robert Crossman October 7, 2026
How to close a merchant account correctly after switching processors: review the contract, complete the processor cutover, stop new transactions at the right time, settle and reconcile pending items, submit cancellation by the required written method, get written closure confirmation, document equipment return, track reserves and trailing fees, and monitor final statements and bank debits.
Stopping transactions does not necessarily terminate a merchant processing agreement. Processing inactivity and contractual termination are different events, and an unused merchant ID can remain open if the processor’s required cancellation procedure was never completed.
The same applies to unplugging a terminal or moving transactions to another provider. Public processor agreements illustrate why: termination provisions can separately address notice, reserves, chargebacks, equipment, and obligations that survive termination.
Fiserv Canada’s published Merchant Terms, for example, contain distinct provisions for termination, reserve funding, equipment, and continuing chargeback liability. Those provisions are processor-specific—not an industry timetable.
How to Close a Merchant Account Without Leaving Loose Ends
Treat merchant account termination as a financial closeout rather than an administrative phone call. The practical sequence for how to close a merchant account is:
- Pull the merchant agreement, amendments, fee schedules, and equipment terms.
- Find the contract term, renewal date, notice method, and termination-cost provisions.
- Confirm the replacement processor is working before stopping the old account.
- Choose the final processing date and complete the last capture and batch.
- Reconcile pending funding, refunds, reversals, and open disputes.
- Send cancellation exactly as the contract requires.
- Return processor-owned, rented, or leased equipment as required.
- Obtain written closure, final-fee, and reserve-release information.
- Review subsequent statements and processor ACH debits until everything matches.
If the replacement account is not fully tested yet, use a controlled transition rather than prematurely shutting down the old processing path. The operational steps for switching merchant service providers smoothly are closely related to the closure process.
Start With the Merchant Agreement, Not a Phone Call
Your merchant processing agreement controls the required cancellation method. Written notice requirements may appear in the original application or agreement, incorporated terms and conditions, a program guide, an amendment, or a separate notice provision.
Any checklist for how to close a merchant account should therefore begin by locating the controlling documents. A salesperson or support agent saying that an account is “canceled” may be useful evidence, but it may not satisfy a contract requiring a particular form, recipient, or delivery method.
Possible contractual procedures include a signed cancellation form, written letter, authenticated portal request, designated email address, or trackable mail. Do not assume that a method accepted by one processor works with another.
Find These Clauses First
- Contract term and effective date
- Automatic-renewal provision
- Renewal date
- Required advance notice, if any
- Permitted cancellation-delivery method
- Early termination fee
- Liquidated-damages formula
- Equipment purchase, rental, or lease obligations
- Reserve and security-interest language
- Continuing liability after termination
- Processor ACH authorization
- Survival clauses
- Separate gateway or software commitments
Write down the actual clause references. That creates a contract-based closure plan instead of relying on someone’s memory of the sales conversation.
Merchant Account Cancellation Letter: What to Put in Writing
A useful merchant account cancellation letter should identify the account precisely, state the requested effective date, and force unresolved money and equipment questions into the written record. Do not include card numbers, CVVs, customer payment details, passwords, or other sensitive cardholder data.
Adapt this model to the notice method required by your agreement:
Subject: Merchant Account Termination Request
Please treat this as notice to terminate the merchant processing account for [legal business name], Merchant ID [MID], effective [requested date], subject to the termination provisions of our agreement.
Our intended final processing date is [date].
Please confirm in writing:
- the effective termination date and all MIDs covered;
- any early termination amount and the contractual basis/calculation;
- required equipment returns or other hardware obligations;
- the current reserve or held-funds balance;
- the reserve release or review schedule;
- any recurring or surviving charges;
- the expected final statement date; and
- that routine service fees will not continue accruing after effective termination except for legitimate obligations that survive under the agreement.
Please provide written confirmation when termination has been completed.
[Authorized signer / contact information]
Keep the submitted version and proof that it reached the contractually designated destination.
Time the Final Batch Settlement Before You Shut Everything Down
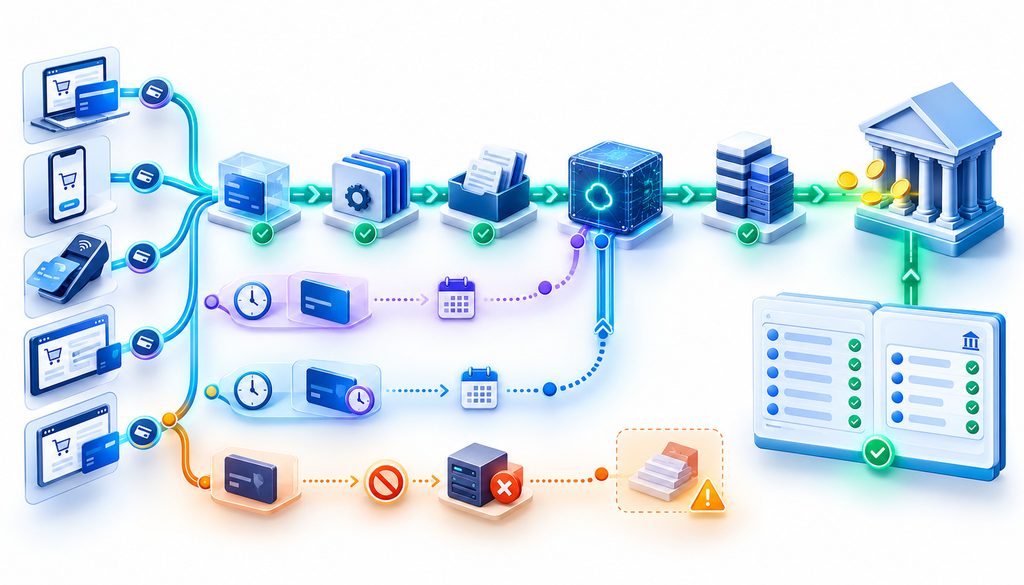
Do not choose the shutdown time solely from the date of the last sale. A transaction can be authorized first, captured later, included in a batch, submitted for settlement, and funded to the merchant’s bank after that.
Authorization confirms that a transaction can proceed; capture records the amount to be collected. Batching groups captured transactions for settlement, while funding is the later movement of net or gross proceeds into the merchant’s bank account. A pending authorization, reversal, tip adjustment, delayed capture, or refund can therefore remain unresolved after the customer’s checkout is finished.
For a deeper breakdown of these stages, see payment authorization versus settlement.
An illustrative final batch settlement workflow, not a universal processor timetable, looks like this:
- Day 1: Stop sending new transactions to the outgoing account.
- Day 1: Capture eligible open transactions and finalize the last batch.
- Following settlement period: Match processor settlement reports to bank deposits and investigate exceptions.
- After pending items are reconciled: Complete shutdown according to the contract.
How to close a merchant account safely becomes more complicated for restaurants with tip adjustments, lodging businesses with delayed completion, card-not-present merchants with delayed capture, and subscription businesses with recurring transactions. Map those workflows before disabling the old gateway or credentials.
Do Not Forget Refunds After the Processor Switch
Before termination, ask the outgoing processor exactly how refunds for its historical transactions will work after account closure. Refund functionality may remain available for a period under one arrangement but disappear with account or gateway access under another.
Confirm whether the processor will debit refund funding from the settlement bank account, use held funds, or require another approved process. Also ask how a negative balance will be collected.
Keep old and new processor transactions separate in reconciliation. Do not improvise by turning a refund into an unrelated card transaction; establish the outgoing provider’s approved refund method before terminating access.
What Happens to Reserves and Held Funds After Account Closure?
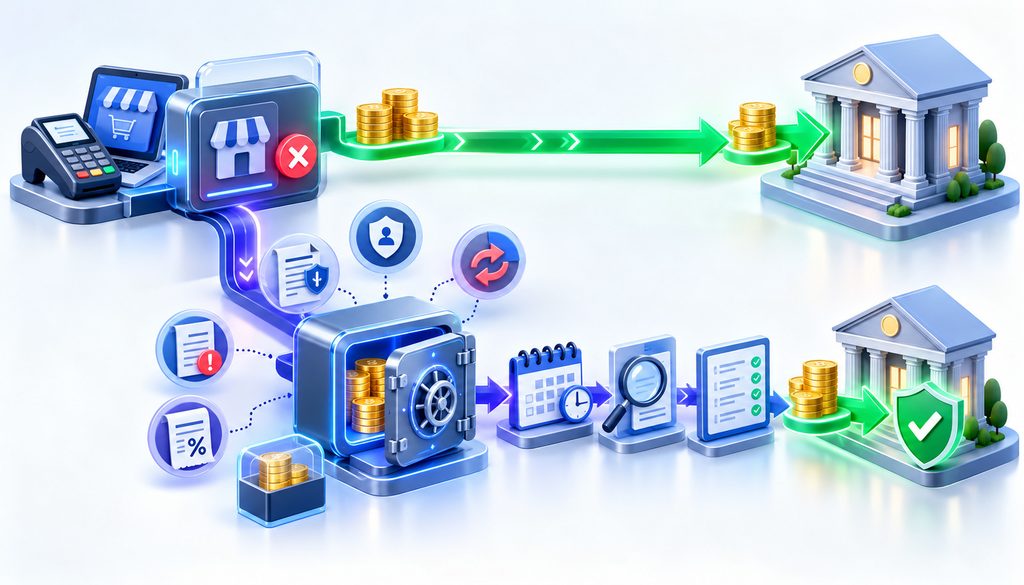
Closing the merchant account does not automatically make every reserve immediately payable. The governing reserve provision determines what remains held, what liabilities the funds secure, and when the balance is released or reviewed.
A merchant reserve may be structured as a rolling reserve, fixed reserve, security reserve, risk hold, or withheld settlement balance. Contracts may permit reserved funds to secure chargebacks, refunds, reversals, fees, or other surviving liabilities.
A merchant reserve may be structured as a rolling reserve, fixed reserve, security reserve, risk hold, or withheld settlement balance. The processor’s contract determines what the reserve secures and what happens after termination.
For example, Fiserv Canada’s published Merchant Terms show how one processor expressly connects termination with reserve funding and allows reserved funds to remain available for chargebacks, adjustments, processing charges, and other contractual liabilities. That is a processor-specific example, not a release timetable merchants should apply to another provider.
Fiserv Canada’s published terms are a useful illustration of the contract-specific nature of this issue: that agreement separately defines post-termination reserve funding and continuing transaction liability. Its particular timetable should not be applied to a different processor.
For reserve release after account closure, request the following in writing:
| Question to Confirm | Why It Matters |
| Current reserve balance | Establishes what is actually being held |
| Contract provision | Identifies the authority for continued restriction |
| Expected release or review date | Creates a follow-up date |
| Permitted deductions | Explains possible reductions |
| Final reconciliation | Shows what was released, deducted, or retained |
Do not accept “the reserve releases later” as the final record. Ask for a dated schedule or review point and an escalation contact.
Early Termination Fees: Flat Fees vs. Liquidated Damages
A merchant account early termination fee exists only if the applicable agreement creates one. Before paying or disputing anything, obtain the relevant provision and an itemized calculation.
| Structure | How It Works | What to Request |
| Flat termination fee | Predetermined contractual amount | Clause, effective contract term, invoice |
| Liquidated damages | Formula defined by the agreement; may consider remaining term or specified fees | Complete formula, inputs, remaining term, calculation |
| Other closure cost | Equipment, gateway, unpaid service, minimum, or other commitment | Separate agreement and billing period |
A merchant trying to cancel a merchant account without fees should first determine whether the contract term has expired, whether the account is month-to-month, and whether the processor has approved a waiver.
Processors may voluntarily waive a fee after documented service problems, negotiated migrations, or other circumstances. A contract change may also create cancellation rights if the agreement expressly says so. Do not assume a waiver is legally mandatory unless the applicable contract or law actually creates that right.
Most importantly, do not replace this analysis with an ACH block. Blocking the processor at the bank does not itself terminate the underlying merchant agreement and can interfere with legitimate final adjustments, creating a separate balance dispute.
Do Not Confuse Merchant Processing With an Equipment Lease
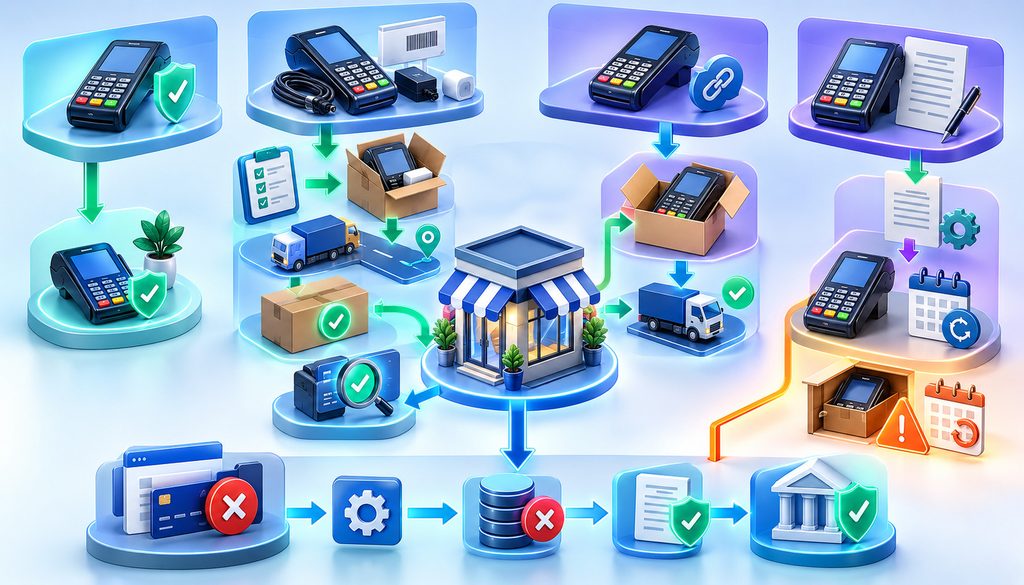
Processing, hardware, and software can be governed by different contracts. A terminal might be purchased outright, rented, provided under a free-placement program, loaned, or covered by a separate lease.
A “free” terminal therefore does not necessarily become merchant property. Current Heartland ancillary terms provide one real example: certain rented hardware remains Heartland’s property, and the terms separately address return and billing obligations. That is one provider’s arrangement, not a universal equipment rule.
A “free” terminal therefore does not necessarily become merchant property. Hardware ownership and return duties should be verified from the applicable equipment agreement.
As a real contract example, Heartland’s current Ancillary Products and Services Terms state that rented hardware remains Heartland property and that rental billing continues until Heartland receives the equipment. Those terms apply to that particular Heartland arrangement and should not be treated as an industry-wide return rule.
For every payment terminal return:
- Record manufacturer, model, and serial number.
- Photograph the device and accessories.
- Obtain the required return authorization.
- Use trackable shipping.
- Insure valuable equipment when appropriate.
- Keep the shipping receipt and delivery confirmation.
- Request written acknowledgment of receipt.
- Confirm when rental or non-return billing should stop under the equipment agreement.
Do not discard equipment until ownership is established.
The Fees That Can Follow You After Closure
A merchant statement after cancellation is not automatically evidence of improper billing. The key question is what the charge represents and when the underlying obligation arose.
Separate trailing merchant fees into four categories:
- Pre-termination cost billed afterward: Final-month processing fees, an already-incurred annual or PCI-related charge, or another accrued item may post after the effective termination date if the contract permits it.
- Obligation that survives termination: Chargeback fees, refunds, negative-balance recovery, reserve adjustments, or other contractually surviving liabilities may remain collectible.
- Separate service never canceled: A gateway, software platform, equipment rental, or third-party subscription may have its own cancellation process.
- Potentially erroneous recurring billing: New monthly, statement, PCI, minimum, or other routine service charges extending beyond the agreed closure date without an identifiable contractual basis deserve investigation.
Do not assume a monthly minimum, annual fee, PCI fee, or statement fee can continue indefinitely. Ask for the contract clause, billing period, service dates, and effective termination date.
Use the final statements the same way you would analyze an active account. These explanations of how to read a merchant processing statement and common merchant-statement billing errors provide useful reconciliation frameworks for residual processor billing.
Chargebacks Can Outlive the Merchant Account
Merchant account closure does not erase liability connected with transactions processed before termination. Keep receipts, order records, fulfillment evidence, transaction IDs, customer communications, and any information needed to respond to disputes.
Confirm how post-termination chargebacks will be funded and where dispute notices will be sent. Keep reserve correspondence and maintain current contact information with the former processor.
There is no single universal period during which every chargeback can occur. Dispute conditions depend on network rules, dispute category, transaction circumstances, and the merchant’s agreement. Visa directs merchants to its current rules while also emphasizing applicable regional rules and the merchant’s acceptance agreement with its acquirer.
Prevent the “Zombie Merchant Account”
A zombie merchant account is an account the business believes is canceled even though billing continues because formal closure was incomplete, another MID remains active, or an attached service was never terminated.
The documentation stage is therefore central to how to close a merchant account. Keep:
- Signed cancellation request and proof of delivery
- Written processor cancellation confirmation
- Effective termination date
- Every MID covered by the request
- Final batch report and final statement
- Settlement reconciliation
- Equipment tracking and receipt confirmation
- Termination-fee calculation or waiver
- Reserve balance and release correspondence
- Final reserve reconciliation
- Gateway/software cancellation confirmation
- Copies of later processor debits and statements
Multi-location companies should confirm every MID individually. A useful companion is the operational distinction between one MID and multiple MIDs across locations and channels.
A Clean Merchant Account Closure Timeline
The safest way to think about how to close a merchant account is as a series of checkpoints. A planning window of 30–90+ days can be useful when researching and preparing, but it is not a universal notice requirement; the contract supplies the actual deadline.
| Stage | Merchant Action | Document to Keep | Risk if Missed |
| Planning period | Review contract and renewal provisions | Agreement/amendments | Unexpected renewal or fee |
| Migration testing | Verify new processor end to end | Test records | Lost sales after cutover |
| Final processing date | Route new sales away from old MID | Cutover record | Transactions split unexpectedly |
| Final batch | Capture and reconcile open items | Batch/settlement report | Missing funding |
| Refund planning | Confirm old-transaction refund path | Processor instructions | Refund failures |
| Formal notice | Use contract-required method | Notice/proof of delivery | Account stays open |
| Equipment return | Follow hardware agreement | Tracking/receipt | Rental or non-return charge |
| Closure confirmation | Obtain effective date in writing | Confirmation | Zombie account |
| Post-closure review | Examine statement and ACH activity | Statements/bank records | Unnoticed residual billing |
| Reserve follow-up | Track stated review/release date | Reserve correspondence | Held funds overlooked |
| Final reconciliation | Match every remaining amount | Final reconciliation | Unresolved balance |
Real-World Example: Closing an Old Account After a Processor Switch
A retailer has its replacement processor running successfully but still has one open batch, several recent purchases that could require refunds, a processor-owned terminal, a reserve balance, and a termination provision in the old agreement.
The retailer first reconciles and settles the open batch. It confirms the post-switch refund method, records the reserve balance, submits notice as the contract requires, obtains written termination confirmation, returns the terminal with tracking, reviews subsequent statements, and follows the documented reserve-release path.
Bad approach: Stop processing, block every processor ACH debit, put the terminal in storage, and assume cancellation happened.
Better approach: Reconcile → notify → confirm → return equipment → monitor charges → track reserve → retain documentation.
Common Mistakes When Closing a Merchant Account
Avoid these preventable closure failures:
- Assuming the new processor automatically cancels the old one
- Relying entirely on verbal cancellation
- Terminating access before the final batch settles
- Forgetting historical refunds
- Blocking ACH before reconciling legitimate obligations
- Assuming reserves must be released immediately
- Treating processing cancellation as equipment cancellation
- Forgetting a separate gateway or software subscription
- Returning hardware without tracking
- Discarding historical transaction records
- Failing to obtain written closure confirmation
- Checking one MID while another location remains active
The recurring theme is simple: the contract, money flow, hardware, and records all have to close together.
Before You Send the Cancellation
Use this final decision box:
- I found the termination clause.
- I confirmed the current contract or renewal date.
- I know the required notice method.
- I know whether an early termination fee applies.
- My final transactions are captured and batched.
- I have a plan for refunds and disputes.
- I documented the reserve balance.
- I confirmed equipment ownership or return requirements.
- I canceled separate gateway/software services where necessary.
- I requested written termination confirmation.
- I know when to expect the final statement.
- I have a date to follow up on reserve release.
Expert Insight: [Editorial team can insert a verified processor-risk, payments-law, or merchant-services expert quotation here.]
The strongest expert contribution would explain why merchants should document both the effective termination date and the processor’s continuing reserve, dispute, and equipment obligations rather than treating cancellation as a single event.
FAQs
How much notice do I need to close a merchant account?
There is no universal notice period. Read the termination and notice clauses in the current merchant processing agreement, including amendments and renewal provisions. Give notice by the specified deadline and method, and retain delivery evidence.
Can I cancel a merchant account without paying an early termination fee?
Possibly. First determine whether your contract actually imposes a fee at the time you terminate. Check the contract term, renewal status, any liquidated-damages language, contractual cancellation rights, and whether the processor has agreed to a waiver.
Should I close my bank account after canceling the processor?
Do not use bank-account closure as a substitute for processor cancellation. First reconcile expected deposits, refunds, chargebacks, fees, reserve adjustments, and authorized final debits. If you later plan to change the settlement account, coordinate that decision with the obligations that remain outstanding.
How long does it take to receive reserve funds after closing a merchant account?
There is no industry-wide reserve-release period. The reserve agreement controls the release or review mechanics, and remaining chargebacks, refunds, fees, or other liabilities can affect the balance. Get the reserve amount and expected release or review date in writing.
Can a processor charge me after my merchant account is closed?
Yes, in some circumstances. A legitimate charge may have been incurred before termination, may represent a surviving contractual obligation, or may come from a separate service agreement. Routine recurring fees continuing without an apparent contractual basis should be challenged and documented.
What happens if I do not return the payment terminal?
If the processor, lessor, or rental provider owns the terminal, the applicable agreement may permit continued rental, non-return, replacement, or other charges. Check the equipment contract rather than assuming a “free” or previously installed device belongs to the business.
Can customers still dispute transactions after the merchant account is closed?
Yes. Closing the account does not eliminate dispute rights or merchant liabilities associated with earlier transactions. Preserve transaction and fulfillment evidence and confirm how the former processor will communicate and fund post-termination disputes.
Close the Merchant Account Only After the Money and Paperwork Match
The central rule for how to close a merchant account is that the exit is not complete when the terminal stops accepting cards. It is complete when the final batch is reconciled, contractual notice is satisfied, equipment is accounted for, fees have an explanation, reserves have a documented release path, and the processor confirms closure in writing.
Put the effective closure date and reserve follow-up date on your accounting calendar. Then keep checking statements and bank activity until every remaining amount has been reconciled.